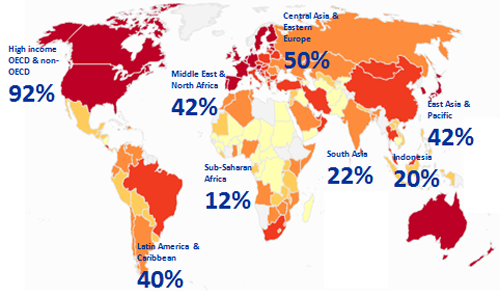
Source:
Findex-WorldBank-2011
Financial inclusion emerged as a trending
topic after the 2008 crisis, primarily due to
the crisis impact on those at the bottom of the
pyramid (low and irregular income, isolated,
living with disabilities, undocumented workers,
disadvantaged communities), who are typically
unbanked and numerous in developing economies.
At the G20 Pittsburgh Summit in 2009, G20
members agreed to increase access to finance for
this group, which was subsequently reiterated at
the Toronto Summit in 2010, by issuing nine
Principles for Innovative Financial Inclusion as
development guidelines for financial inclusion,
namely leadership, diversity, innovation,
protection, empowerment, cooperation, knowledge,
proportionality and frameworks.
Since then, numerous international forums
have focused on financial inclusion, such as
CGAP, World Bank, APEC, Asian Development Bank
(ADB) and the Alliance for Financial Inclusion
(AFI), as well as international standard-setting
bodies, namely the Bank for International
Settlements (BIS) and Financial Action Task
Force on Money Laundering (FATF), including
developing economies like Indonesia.
Financial
Inclusion
Lacking a standard definition of financial
inclusion, several international institutions
have put forward the following definitions:
"A state in which all working age adults
have effective access to credit, savings,
payments, and insurance from formal service
providers. Effective access involves convenient
and responsible service delivery, at a cost
affordable to the customer and sustainable for
the provider, with the result that financially
excluded customers use formal financial services
rather than existing informal options" (CGAP-GPFI).
"Financial inclusion involves providing
access to an adequate range of safe, convenient
and affordable financial services to
disadvantaged and other vulnerable groups,
including low income, rural and undocumented
persons, who have been underserved or excluded
from the formal financial sector" (FATF).
"The process of ensuring access to
appropriate financial products and services
needed by all sections of the society in general
and vulnerable groups such as weaker sections
and low-income groups in particular, at an
affordable cost in a fair and transparent manner
by regulated, mainstream institutional players"
(RBI/Reserve Bank of India).
Why Do We
Need
There are many supply (service providers) and
demand-side (consumers) reasons for those
languishing at the bottom of the pyramid to
remain unbanked, including price barriers,
information barriers, product design barriers
and channel barriers. In response, financial
inclusion overcomes those barriers by providing
a wealth of benefits to be enjoyed by consumers,
regulators, the government and private sector as
follows:
Increasing economic efficiency
Supporting financial system stability
Reducing shadow banking and
irresponsible finance
Supporting financial market deepening
Unlocking potential new markets for
the banking industry
Raising the Human Development Index
(HDI)
Contributing to sustainable local and
national economic growth
Reducing inequality and low-income
trap rigidity, thus ameliorating public
prosperity and ultimately alleviating
poverty
How to
Implement
Around the world, governments are combating
financial exclusion through two salient
approaches. First, a comprehensive national
strategy, such as those implemented in
Indonesia, Nigeria and Tanzania. Second, a range
of separate programs, for instance financial
education, as pursued by the US Administration
since the 2008 crisis. In general, a
comprehensive national strategy contains three
key aspects, namely providing appropriate
services, providing appropriate products as well
as responsible finance through financial
education and consumer protection. Financial
inclusion is typically implemented in stages,
starting with a clear target, such as the
recipients of government social aid or migrant
workers, before gradually rolling out to the
public in general.
Who
Implements
The financial inclusion strategy is not an
isolated initiative and, therefore, not only
involves the participation of Bank Indonesia yet
also the regulator, government ministries and
other institutions to offer financial services
to the public. Through the national financial
inclusion strategy, close and structured
collaboration between the government and various
other stakeholders is expected.


