Financial market infrastructures (FMI) refer
to all parts of the financial system that facilitate financial market
transactions, including settlement. According to IOSCO, an FMI is
defined as a multilateral system among participating financial institutions,
including the operator of the system, used for the purposes of recording,
clearing or settling payments, securities, derivatives or other financial
transactions. Several systems are considered systemically important
financial market infrastructures based on the criteria set by each
respective country. Nevertheless, most definitions refer to post-trade
systems.
Referring to the Principles for
Financial Market Infrastructures (CPSS-IOSCO, 2012), FMIs are categorized as
systemically important if they involve multilateral systems for the
following functions: Payment System (PS), Central Securities Depositories
(CSD), Securities Settlement System (SSS), Central Counterparty (CCP) and
Trade Repository (TR). In its implementation, each jurisdiction has
full discretion on whether to consider a system a systemically important
FMI. For example, New Zealand does not consider a trade repository
(TR) a systemically important FMI because it is not currently included in
the regulatory framework. India has designated its trading system, namely
the Negotiated Dealing System-Order Matching (NDS-OM) in the government
securities market, as an FMI because it dominates 90% of the transaction
volume of government securities in the secondary market.
In Indonesia, the Bank Indonesia – Real Time Gross Settlement (BI-RTGS)
system as well as the Bank Indonesia – Scripless Securities Settlement
System (BI-SSSS) are categorized as systemically important FMIs, both of
which are owned, operated and supervised by Bank Indonesia.
In addition, FMIs are also operated by self-regulatory organizations (SROs),
as regulated and supervised by the financial market authority. In
terms of the capital market, the Indonesia Stock Market Clearing House
(KPEI) and the Indonesian Central Securities Depository (KSEI) fall under
the authority of the Indonesian Financial Services Authority (OJK).
Regarding, commodity futures trading, PT Kliring Berjangka Indonesia
(persero) and the Indonesia Clearing House (ICH) are under the jurisdiction
of the Commodity Futures Trading Regulatory Agency (BAPPEBTI).
To illustrate the role of FMIs, businesses require a Payment System (PS) to
receive payment transactions for goods and services. The public uses a
payment system to receive salary and allowance payments. Central
Securities Depositories (CSD) administrate equity and bond transactions
securely and efficiently, while Central Counterparties (CCP) reduce
counterparty risk by providing clearing and settlement services for
over-the-counter (OTC) derivatives without going through an exchange.
Why regulate FMI?
Considering the
crucial role of FMIs in financial markets in the event of operational
constraints, which could undermine the financial markets contribution to
economic development financing and even trigger financial system instability
risk if not well-managed, financial sector authorities around the world are
recognising the importance of FMI regulation and supervision.
Regulation and supervision typically involve the minimum requirements for an
FMI operator and the coordination mechanism for domestic financial
authorities and international authorities if the FMI is providing
cross-border transactions.
Fundamentally, strengthening an FMI must strike an optimal balance between
increasing financial market efficiency and development and minimizing the
potential risks that could disrupt financial system stability.
Therefore, identifying the types of risk associated with an FMI is crucial
for the authorities to implement the regulatory and supervisory functions.
A clear and comprehensive supervisory framework based on a solid legal
foundation and covering all aspects of the FMI business is a prerequisite
for effective and efficient FMI regulation and supervision.
How are FMIs regulated?
The regulatory approach to FMIs fundamentally
relates to the legal and regulatory system governing the financial sector of
a country.
In line with the legislation in the financial sector and related authorities
in Indonesia, especially Law No. 4 of 2023 on Financial Sector Development
and Strengthening (“PPSK Law"), the current regulation of FMI in Indonesia,
in addition to being related to the payment system, is carried out through a
financial market segment approach consisting of money and forex markets,
capital markets and commodity markets, including derivative markets. The
issuance of the PPSK Law emphasizes Bank Indonesia's authority in
regulating, developing, and supervising FMIs in the Money Market and Foreign
Exchange Market. FMIs regulated in the PPSK Law include trading venue,
clearing, and/or central counterparty, securities settlement system, central
securities depository, payment system, and trade repository of financial
instruments and/or derivatives.
The
regulatory approach of FMIs is also reflected in the framework for the
development and deepening of Indonesia's financial markets, which is a joint
effort of the relevant authorities in the financial markets, namely the
Ministry of Finance, Bank Indonesia, and the Financial Services Authority.
This framework for financial market development and deepening in Indonesia
is known as the National Strategy for Financial Market Development and
Deepening (SN-PPPK).
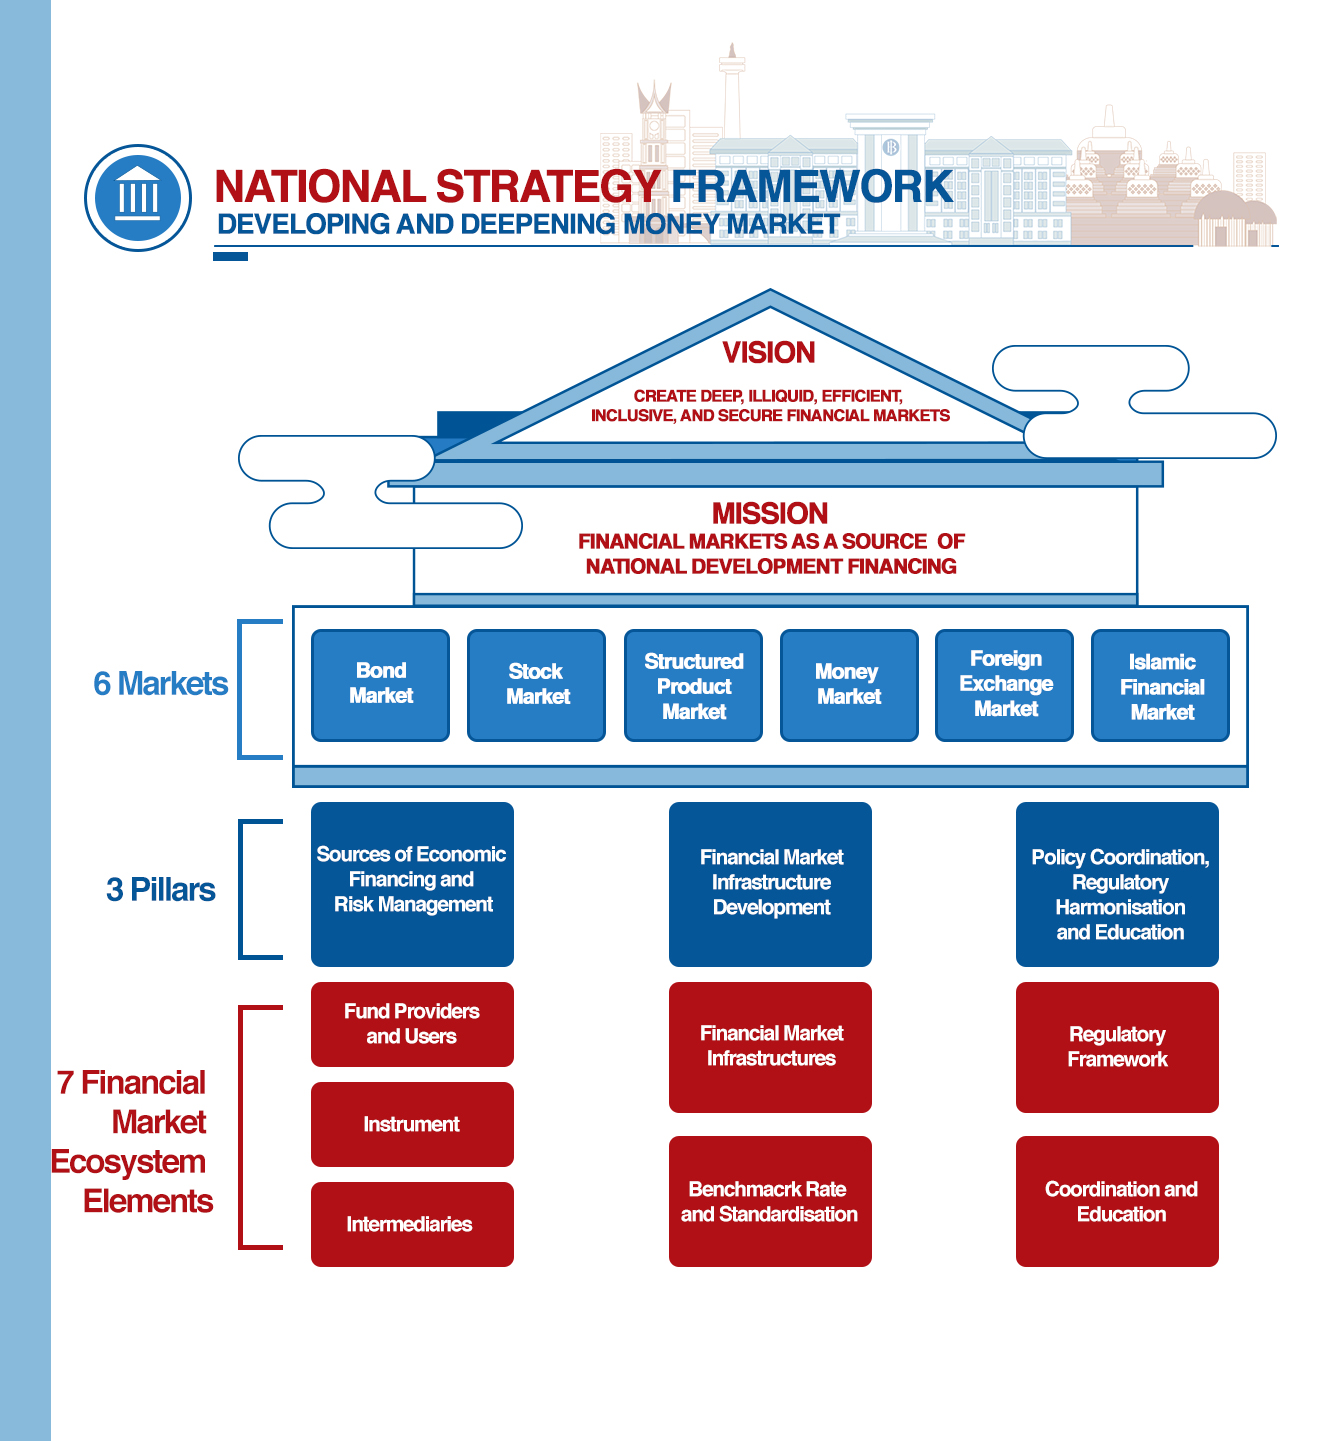
Figure:. National Financial Market Development
and Deepening Strategy Framework
That approach is reflected in the financial
market deepening and development framework, as a joint concern of the
relevant authorities, namely the Ministry of Finance, Bank Indonesia, and
the Indonesian Financial Services Authority (OJK). In Indonesia, the
financial market deepening and development framework is known as the
National Financial Market Development and Deepening Strategy (SN-PPPK),
which is a comprehensive and measured single policy framework directed
towards realizing the vision of deep, liquid, efficient, inclusive, and
secure financial markets. SN-PPPK stipulates three main pillars underlying
the development framework, namely: (i) sources of economic financing and
risk management; (ii) financial market infrastructure development; and (iii)
policy coordination, regulatory harmonization, and education.
Financial market infrastructure development is a key pillar that is expected
to support access to information as well as rapid, secure and efficient
transaction settlement. To that end, inter-authority coordination in
terms of developing the FMIs under each respective authority is essential.
FMI development in Indonesia refers to best international practices adjusted
to the local profile, conditions, policy preferences and national interest,
which is currently considered the best approach. FMI regulation is
constantly aligned with principles adopted internationally, specifically by
the Committee on Payment and Settlement Systems (CPSS) and the International
Organisation of Securities Commissions (IOSCO) as contained in the
Principles for Financial Market Infrastructures (PFMI) (BIS, 2012).
Why
must BI regulate FMI?
Guaranteeing the operational continuity of
reliable, secure, and efficient FMIs vis-à-vis the purview of authority and
responsibilities necessitates an unambiguous regulatory and supervisory
framework.
Legally mandated as the
monetary authority and the Money Market and Foreign Exchange Market, Bank
Indonesia is authorized to regulate and supervise the money market and
foreign exchange market, including those based on Islamic principles.

Figure:. FMIs Play an Important Role in terms
of Monetary Policy Transmission, Payment System Function and Financial
System Stability
More specifically, to strengthen Bank Indonesia's role in the payment system
in Indonesia, Bank Indonesia released the Indonesia Payment System Blueprint
(BSPI) for 2025 in 2019, which aims to support national digital economic and
financial integration and, therefore, safeguard the central bank functions
of currency circulation, monetary policy, and financial system stability,
including financial market infrastructure development.
As one of the initiatives contained in the Indonesia Payment System
Blueprint (BSPI) for 2025, financial market infrastructure development will
be achieved through infrastructure modernization and strengthening the
regulatory framework for financial market infrastructures in line with best
practices to support optimal policy implementation. The key
deliverables of this initiative include the modernization of BI-RTGS,
BI-SSSS (including the CSD function), and the Bank Indonesia-Electronic
Trading Platform (BI-ETP), while strengthening the regulatory framework in
relation to CCP and TR development.
Indonesia as Part of the
International Community
The lessons learned from the Global Financial Crisis in 2008 have motivated
all countries to strengthen global financial market resilience through
stronger policies and supervision in each jurisdiction, including
infrastructures.
As part of the G20, FMI development in Indonesia has been accelerated
through efforts to meet the OTC Derivatives Market Reform mandate as a G20
initiative of the Pittsburgh Summit in 2009. The efforts aim to
increase transparency, prevent market abuse, and mitigate systemic risk
through five key agenda items for OTC derivatives market reforms as follows:
-
Standardised OTC derivatives must be transacted through Electronic Trading
Platforms (ETP) or exchanges.
- Standardised OTC derivatives must be
cleared through a Central Counterparty (CCP).
- Standardised OTC
derivatives must be reported through a Trade Repository (TR).
- OTC
derivative transactions not cleared through a CCP will be subject to higher
capital charges.
- OTC derivative transactions not cleared through a
CCP will be subject to margining rules.
Implementation of the five agenda items with a focus on derivatives
transactions is expected to reinforce domestic and global financial market
resilience and, thus, mitigate similar crises, while supporting the
sustainability of healthy financial markets. To that end, Bank
Indonesia is committed to other financial authorities to actively support
efforts to fulfill its mandate in various areas under Bank Indonesia's
authority.
FMIs under the Regulation and
Supervision of Bank Indonesia
There are currently 3 types of systemically important FMIs under the
regulation and supervision of Bank Indonesia as mandated by the PPSK Law and
in accordance with Bank Indonesia Regulation (PBI) No. 19/14/PBI/2017
concerning Transaction Processing, Securities Administration and Real-Time
Settlement as follows:
-
Bank Indonesia – Real Time Gross Settlement (BI-RTGS) system,
namely an electronic funds transfer system that allows for the instantaneous
(real-time) transfer and settlement of individual transactions (Payment
System function).
- Bank Indonesia – Scripless Securities
Settlement System (BI-SSSS), namely infrastructure used to
administrate transactions and securities electronically (Central Securities
Depositories and Securities Settlement System).
- BI-Fast
Payment (BI-FAST) is Bank Indonesia's payment system infrastructure
to facilitate retail payments that can be accessed at any time.
Referring to the mandate for OTC Derivatives Market Reforms, as well as to
implement the Indonesia Payment System Blueprint (BSPI) for 2025 and
alignment of the PPSK Law, Bank Indonesia is currently developing a Trading
Venue & Central Counterparty for OTC interest rate and exchange rate
derivatives (CCP SBNT) as well as a Trade Repository as follows:

Figure: Bank Indonesia Regulations concerning
FMIs in Indonesia
Moving forward, Bank Indonesia is firmly
committed to financial market infrastructure development to support
deep, liquid, efficient, inclusive, and secure domestic financial
markets that meet international best practices and standards.


